Canadian Dollar Weakness: What It Means for Your Budget
Understanding Canadian Dollar Weakness and Your Money
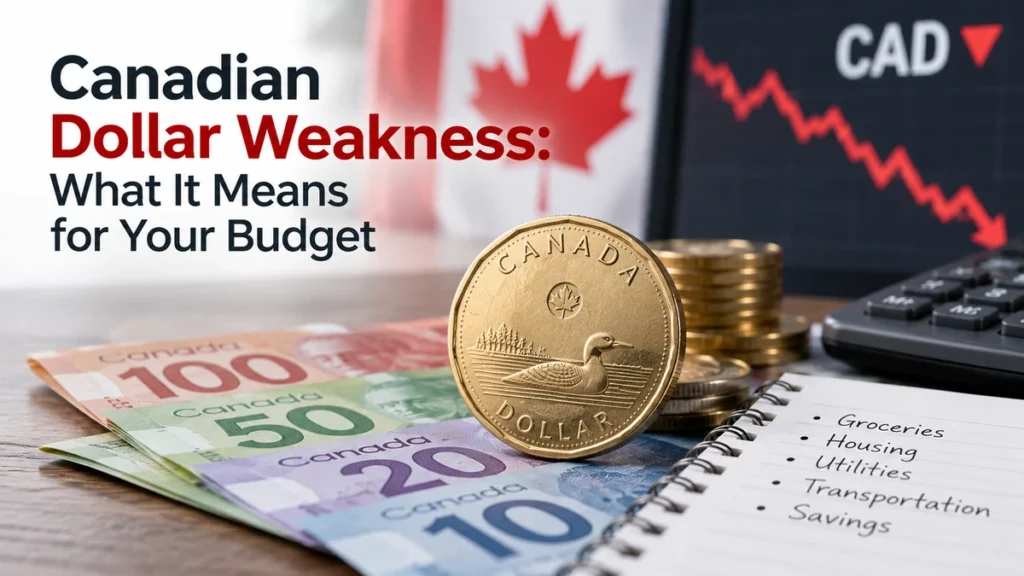
If you’ve been paying attention to financial news lately, you’ve probably heard that the Canadian dollar has been weakening against major currencies. While this might sound like a story that only concerns international traders and economists, the reality is that currency fluctuations have real consequences for your personal finances—especially if you hold savings, make cross-border purchases, or plan to travel.
When a currency weakens, it means that one unit of that currency buys less of another currency than it did before. For Canadian households, this creates a ripple effect that touches everything from grocery prices to investment returns. Understanding what’s happening with currency movements helps you make smarter financial decisions and protect your hard-earned money.
How Currency Weakness Affects Your Daily Budget
The weakening of the Canadian dollar doesn’t just affect exchange rates at the airport. It influences the prices you pay at home. When the Canadian dollar is weaker, imported goods become more expensive because Canadian retailers need to spend more dollars to purchase inventory from other countries. This can push up prices on everything from electronics to clothing to food items.
For your household budget, this means your purchasing power may shrink without your income changing. If you’re shopping on a tight budget, you might notice that your grocery bill creeps up or that certain imported products cost noticeably more. This is why many financial advisors recommend reviewing your spending categories quarterly—especially during periods of currency volatility.
One practical step you can take today: go through your last three months of bank and credit card statements. Highlight the categories where you spend the most money on potentially imported goods. This awareness alone can help you identify where to cut back or find local alternatives.
Interest Rates, Bond Yields, and Your Savings
The article mentions that benchmark yields are slipping, which ties directly to interest rate movements. When bond yields fall, it typically means that returns on fixed-income investments and savings accounts become less attractive. For savers, this is concerning because it reduces the growth potential of money sitting in traditional savings vehicles.
If you’ve been relying on a savings account to generate interest income, lower yields mean you’re earning less on that money. A savings account that once offered a competitive rate might suddenly feel underwhelming. This is the moment many people realize they need to diversify their savings strategy beyond a single account.
Consider spreading your emergency fund and short-term savings across different account types or investment vehicles that might offer better returns during lower-yield environments. Research what options are available to you, but be realistic about risk tolerance—higher returns often come with higher risk.
Protecting Your Budget from Currency Volatility
While you can’t control currency markets, you can control how much your personal finances are exposed to their swings. Here are some practical ways to build resilience into your budget:
- Track your currency exposure. If you hold investments in foreign currencies or receive income from outside your home country, map out exactly how much of your wealth is affected by exchange rates.
- Build a larger emergency fund. Currency weakness often accompanies economic uncertainty. Having 3-6 months of expenses set aside in accessible savings provides a buffer against unexpected financial shocks.
- Review your subscription costs. Many online subscriptions are priced in foreign currencies. During periods of currency weakness, these become more expensive. Audit which subscriptions you actually use and consider canceling the rest.
- Plan major purchases strategically. If you’re planning to buy imported goods or book travel, monitor when the exchange rate is most favorable. Timing purchases around currency strength can yield real savings.
- Diversify your income sources. If possible, consider ways to earn income in multiple currencies. This natural hedging can protect you when one currency weakens.
Smart Budgeting When Economic Conditions Shift
Economic indicators like currency weakness and falling bond yields often signal broader shifts in financial markets. Rather than panic, savvy budgeters use these signals as opportunities to reassess their financial strategies. Think of currency weakness as a wake-up call to review your budget with fresh eyes.
Start by categorizing your expenses into essentials and non-essentials. During periods of economic uncertainty, non-essential spending tends to feel the squeeze first. Identify areas where you can trim without sacrificing quality of life. Maybe it’s reducing dining out, finding cheaper alternatives for regular purchases, or negotiating bills like insurance and internet.
Next, examine your income stability. If your job is in a sector sensitive to economic cycles, consider whether you have adequate savings to weather a potential income disruption. This reinforces the importance of that emergency fund mentioned earlier.
Planning Ahead When Yields Are Low
Lower bond yields mean that traditional “set it and forget it” savings strategies aren’t as effective as they once were. This doesn’t mean you should chase risky investments to compensate. Instead, it’s time to be more intentional about how your money works for you.
Consider automating your savings. By setting up automatic transfers from your checking account to savings or investment accounts, you remove the temptation to spend that money. Even small automatic contributions add up over time, and they force you to live on what remains—a proven budgeting technique.
Also, explore whether you’re taking full advantage of any tax-advantaged savings accounts available to you. These accounts often provide better growth potential than regular savings accounts, especially when market yields are falling.
Common Questions About Currency and Your Budget
Q: If the Canadian dollar is weak, should I convert my savings to another currency?
A: This is a complex decision that depends on your specific situation. Converting all your savings to another currency introduces risk—what if that currency weakens too? Most financial experts recommend keeping the majority of your emergency fund in your home currency for stability and accessibility.
Q: How often should I review my budget when currency is volatile?
A: Review your budget at least quarterly, and more frequently if your income or major expenses are tied to currency fluctuations. Track price changes in categories you know are import-dependent to spot trends early.
Q: Will weak currency ever benefit my personal finances?
A: Yes. If you’re an exporter or freelancer who earns in strong foreign currencies, currency weakness in your home country increases your earnings in local terms. Also, a weaker domestic currency can make exported goods and tourism more attractive, potentially boosting certain industries and job markets.
Start today by reviewing your last three months of spending and identifying your top five expense categories. Then, for each category, research whether imported goods make up a significant portion. This simple audit gives you a clear picture of where currency weakness hits your budget hardest—and where you have the most control to adjust.