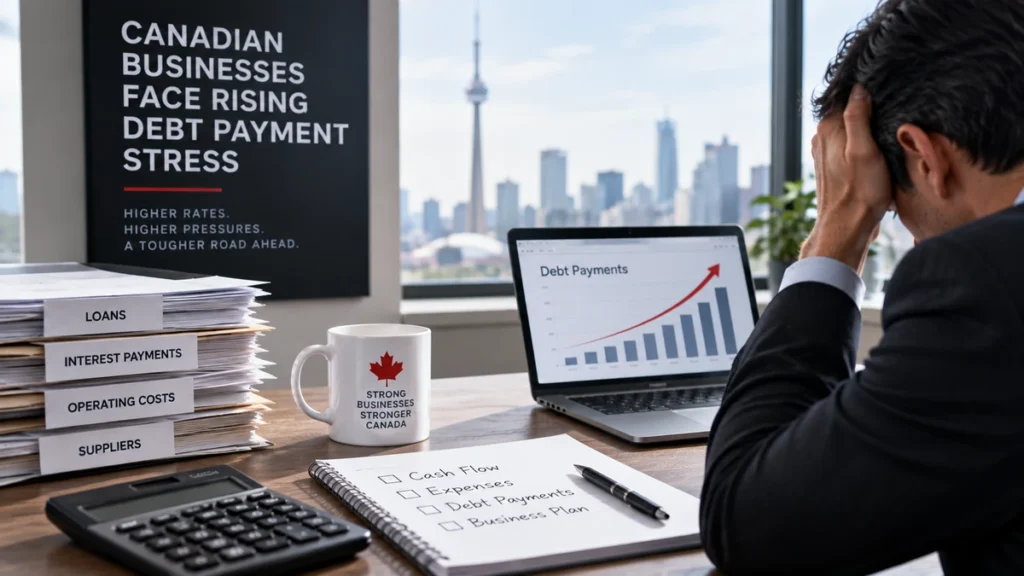
Canadian Businesses Face Rising Debt Payment Stress
Canadian companies struggle with increasing debt burdens, impacting cash flow and financial stability. Learn how businesses manage payment stress and what this means for the economy.
business debt payment stress
Understanding the Rising Debt Challenge for Canadian Businesses
Picture a business owner checking their bank account at month-end, only to realize that debt payments have consumed most of their available cash. This scenario has become increasingly common across Canada, according to recent credit data. Many businesses are now carrying higher debt loads while simultaneously facing tighter margins and slower customer payments.
The challenge isn’t new, but its intensity has shifted. Canadian companies accumulated debt during periods of expansion, economic uncertainty, and unexpected operational disruptions. Now, as interest rates stabilize and economic conditions become less predictable, the weight of servicing that debt grows heavier.
The Cash Flow Squeeze: When Payments Outpace Revenue
Business debt payment stress often stems from a simple math problem: money going out faster than money coming in. When a company owes creditors, suppliers, and lenders on fixed schedules, but customer payments arrive unpredictably, the timing mismatch creates real problems.
Consider a mid-sized manufacturer that extended credit terms to attract larger clients. Those clients might take 60 or 90 days to pay, but the manufacturer still owes suppliers in 30 days. Meanwhile, loan payments on equipment or facilities are due regardless of cash inflow. This gap between when money leaves and when it arrives forces businesses to make difficult choices.
- Delaying payments to suppliers, damaging business relationships
- Reducing inventory or cutting operational expenses
- Taking on additional short-term debt to cover immediate obligations
- Postponing growth investments or equipment upgrades
Each option carries its own consequences, and most businesses end up combining several strategies just to stay afloat.
Why Payment Stress Matters Beyond One Business
When individual companies struggle with debt obligations, the ripple effects spread across the broader economy. Businesses that delay supplier payments force those suppliers to also experience cash flow problems. A small contractor who can’t pay their materials supplier on time might then struggle to meet payroll.
This chain reaction can slow the entire business ecosystem. Economic growth relies on smooth cash flow between companies, and when that flow becomes constrained, opportunities shrink. Businesses cut hiring, delay expansion, and reduce spending on services and materials from other companies.
The stress also shows up in credit metrics. Companies that miss payments or pay late develop damaged credit profiles, making it harder and more expensive to borrow in the future. A business that previously could access a line of credit at reasonable rates might find those options disappearing or becoming prohibitively expensive.
Practical Strategies for Managing Business Debt Obligations
While external economic factors matter, businesses do have tools available to manage debt payment stress more effectively. The key is taking a proactive, organized approach to cash flow rather than reacting to crisis after crisis.
Cash flow forecasting forms the foundation. By projecting inflows and outflows over the next 90 days, a business can anticipate shortfalls before they become emergencies. This isn’t complex—tracking expected customer payments, scheduled debt obligations, payroll, and operational expenses on a simple spreadsheet gives a business owner real visibility.
Prioritizing payments strategically becomes necessary during tight periods. Not all debts are equally critical. Payroll and essential supplier payments that keep operations running need priority. Debt service comes next. Less urgent payments might be negotiated with creditors for later dates.
Negotiating payment terms can create breathing room. A business might approach creditors or lenders to discuss payment schedules during difficult periods. Some creditors prefer slightly delayed payments to outright defaults, and many will work with businesses that communicate proactively rather than simply disappear.
Revenue acceleration directly reduces payment pressure. Strategies like offering early-payment discounts to customers, tightening collection processes, or adjusting pricing can bring cash in faster. Even small improvements in collection timing add up significantly over months.
The Personal Finance Angle: What This Means for Your Household Budget
If you’re a business owner or someone whose household income depends on business performance, this broader business debt stress has personal consequences. When businesses struggle, owners’ personal finances often suffer alongside them.
Taking the same principles that help businesses manage debt payment stress and applying them to personal finances strengthens household resilience. Forecasting your household cash flow for the next three months reveals exactly when money arrives and when it needs to leave. This simple practice prevents the emergency spending and crisis borrowing that destabilize personal budgets.
Prioritizing expenses works at the household level too. Essential expenses—housing, utilities, food, insurance—must be paid first. Debt service comes next to protect credit. Discretionary spending gets adjusted when necessary. This clarity prevents the common mistake of spending money on wants before obligations are covered.
Building a cash buffer of 30 to 60 days’ worth of essential expenses provides the same protection that strong cash flow forecasting provides businesses. When irregular expenses arrive or income dips temporarily, that buffer absorbs the shock without forcing you to take on additional debt.
Developing a Realistic Debt Management Plan
Whether managing business obligations or personal debt, a realistic plan beats wishful thinking every time. Realistic means acknowledging the actual amount owed, the actual payment capacity, and the actual timeline for improvement.
Start by documenting all debts: who you owe, how much, what the monthly obligation is, and when payments are due. Many people and business owners skip this step because the full picture feels overwhelming. But knowing the actual situation is the only foundation for improvement.
Next, identify which debts carry the highest costs. Interest rates vary dramatically—a credit card debt at 20% annual interest costs far more than a car loan at 5%. Paying minimums on everything while directing extra resources toward the highest-rate debt reduces total interest paid and accelerates freedom from debt.
Finally, commit to tracking progress. Monthly reviews of debt balances, payments made, and remaining obligations keep a plan from becoming abstract. Seeing tangible progress—even small decreases in total owed—builds momentum and motivation.
Common Questions About Business and Personal Debt Stress
If my business is struggling with debt payments, when should I seek professional help? Early consultation with an accountant or financial advisor helps before problems become severe. They can review cash flow patterns, identify inefficiencies, and suggest restructuring options before you’re in crisis mode.
Can I negotiate with creditors to reduce what I owe? Many creditors prefer working with borrowers who communicate proactively. Some will agree to reduced payment amounts, extended timelines, or even reduced balances if you’re honest about your situation and show genuine effort to meet obligations.
How long does damaged credit from missed payments take to recover? Late payments stay on credit records for several years, but their impact decreases over time, especially as more recent positive payment history accumulates. Focusing on perfect future payment behavior matters more than dwelling on past problems.
Your Next Step: Take the Forecast Challenge
Whether you’re managing business obligations or personal finances, spend 30 minutes this week mapping your actual cash flow for the next 90 days. Write down every payment obligation you know about and every source of income expected. This single exercise often reveals opportunities for adjustment that prevent problems months down the road.